2026 US Policy Changes: Commercial Energy Storage Project Review
Anúncios
The Latest 2026 US Policy Changes Impacting Commercial Energy Storage Projects: A 3-Month Review
The landscape of commercial energy storage in the United States is in constant flux, driven by an urgent need for grid modernization, increased renewable energy integration, and enhanced energy resilience. As we navigate the early months of 2026, a series of pivotal US energy storage policy changes have begun to reshape the strategic decisions and operational frameworks for commercial energy storage projects across the nation. This comprehensive review delves into the significant developments from January to March 2026, offering crucial insights for developers, investors, and stakeholders in this rapidly evolving sector.
Understanding these policy shifts is not merely an academic exercise; it is fundamental to unlocking new investment opportunities, mitigating risks, and ensuring compliance within a dynamic regulatory environment. The Biden administration’s continued emphasis on clean energy initiatives, coupled with state-level ambitions, has created a fertile ground for energy storage deployment. However, this growth is inextricably linked to the policy mechanisms designed to support it. Our focus here is to dissect the practical implications of these recent changes, providing a clear roadmap for navigating the future of commercial energy storage in the US.
The Evolving Federal Landscape: Key Legislative and Regulatory Updates
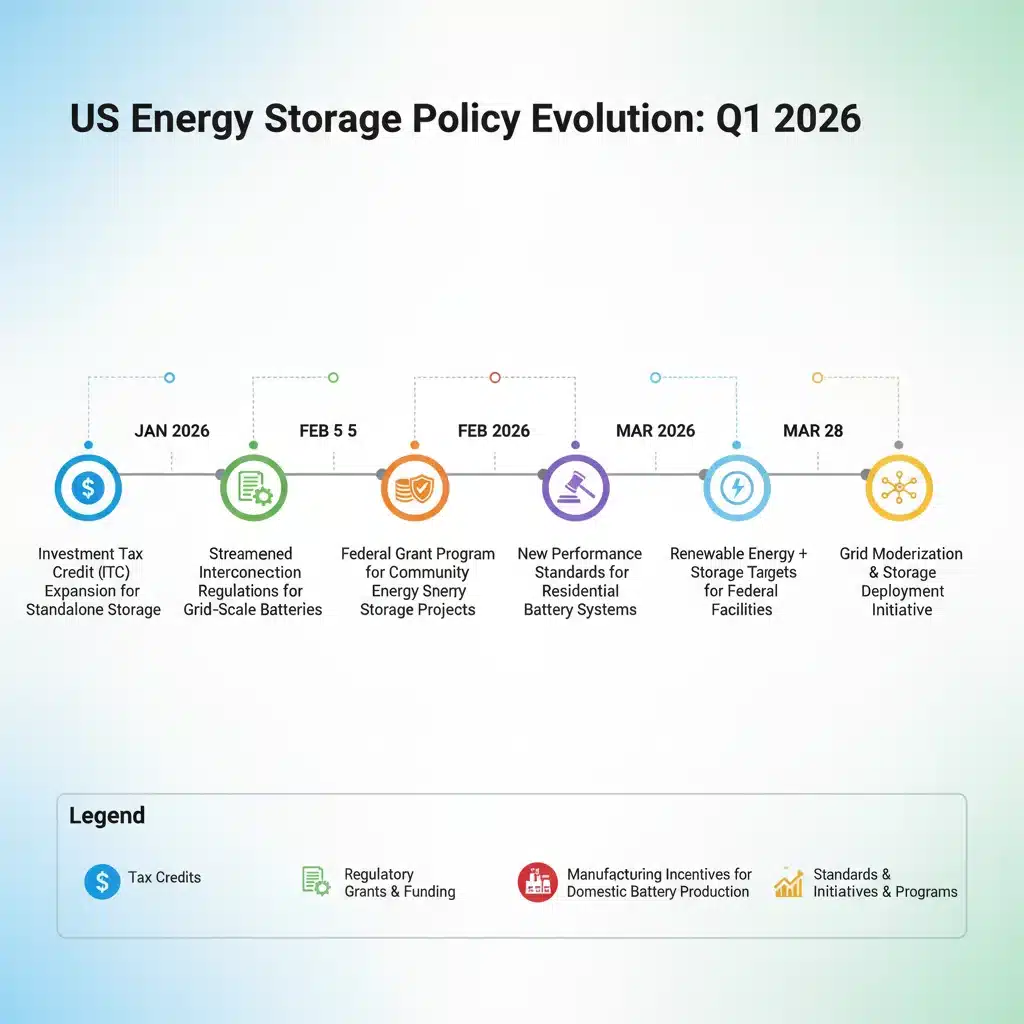
The first quarter of 2026 has witnessed several critical federal adjustments impacting commercial energy storage. Building upon the foundation laid by the Inflation Reduction Act (IRA), new interpretations, clarifications, and supplementary directives have emerged, refining the incentives and requirements for energy storage projects. The IRA’s investment tax credit (ITC) for standalone energy storage, for instance, remains a cornerstone, but recent guidance from the Treasury Department has provided more granular details on eligibility criteria, particularly concerning domestic content requirements and prevailing wage provisions.
One of the most significant federal developments has been the enhanced focus on ‘energy communities’ and low-income communities. New bonus credits within the ITC framework have been finalized, offering additional financial incentives for projects located in areas historically dependent on fossil fuels or those serving disadvantaged communities. This strategic push aims not only to accelerate clean energy deployment but also to ensure equitable distribution of its economic benefits. For commercial developers, identifying and qualifying for these bonus credits has become a paramount consideration, requiring careful project siting and community engagement strategies.
Furthermore, the Department of Energy (DOE) has launched new grant programs and loan solicitations specifically targeting long-duration energy storage technologies. These initiatives, often tied to specific performance metrics and technological advancements, are designed to de-risk innovative solutions that can address grid stability challenges over extended periods. The emphasis is on technologies beyond traditional lithium-ion, encouraging the development and deployment of flow batteries, compressed air energy storage, and other nascent solutions. Understanding the application processes and technical requirements for these competitive programs is essential for companies looking to pioneer next-generation storage solutions.
Beyond direct financial incentives, regulatory bodies like the Federal Energy Regulatory Commission (FERC) have continued to refine rules governing energy storage participation in wholesale markets. While FERC Order 2222, which opened wholesale markets to distributed energy resources, has been largely implemented, subsequent rulings and regional transmission organization (RTO) specific adaptations have clarified market participation models, interconnection procedures, and revenue stacking opportunities. These ongoing adjustments aim to reduce barriers to entry for energy storage, enabling these assets to provide a wider array of grid services, from frequency regulation to capacity support. Staying abreast of RTO-specific market rules is crucial for maximizing revenue streams from commercial storage projects.
The collective impact of these federal actions underscores a clear governmental commitment to accelerating the energy transition. For commercial energy storage developers, this means a more robust, albeit complex, incentive structure and a clearer path for market integration. However, the onus is on project proponents to meticulously navigate the evolving guidelines to fully capitalize on these opportunities.
State-Level Innovations and Regional Disparities
While federal policies provide a broad framework, state-level initiatives often dictate the pace and nature of energy storage deployment on the ground. The first three months of 2026 have seen several states introduce or modify policies that significantly impact commercial energy storage projects, often tailored to their unique energy needs and policy objectives.
California, a perennial leader in renewable energy, has continued to expand its energy storage mandates and incentive programs. Recent updates include increased targets for utility-scale storage procurement and new guidelines for behind-the-meter storage deployment, particularly for commercial and industrial (C&I) customers. The state’s self-generation incentive program (SGIP) has seen adjustments to its budget allocations and eligibility, reflecting a strategic shift towards longer-duration storage and projects that enhance grid resilience during peak demand periods or wildfire events. Developers in California must meticulously track these evolving state mandates and incentive structures, which are often more prescriptive than federal guidelines.
Northeastern states, particularly New York and Massachusetts, have also demonstrated strong commitment. New York’s ambitious energy storage targets have been reinforced with new funding mechanisms and streamlined permitting processes for large-scale projects. Massachusetts, on the other hand, has focused on integrating storage with offshore wind projects, offering incentives for co-located assets that can firm up intermittent renewable generation. These regional efforts highlight a growing trend: states are increasingly viewing energy storage not just as an ancillary service but as a foundational component of their clean energy infrastructure.
Conversely, some states in the Midwest and Southeast are just beginning to establish comprehensive energy storage policies. While federal incentives apply nationwide, the absence of strong state-level mandates or dedicated incentive programs can slow down deployment in these regions. However, even in these areas, utility-specific programs and pilot projects are emerging, often driven by grid modernization efforts and the need to manage growing renewable penetration. Commercial developers need to conduct thorough due diligence on state regulatory environments and utility procurement plans, as these can vary significantly and present both opportunities and challenges.
The interplay between federal and state policies creates a complex but often synergistic environment. Federal tax credits can significantly de-risk projects, while state incentives can bridge financing gaps, particularly for projects with specific local benefits or technological profiles. Navigating this multi-layered policy landscape requires a nuanced understanding of both national directives and localized regulatory frameworks. Developers who can effectively leverage both will be best positioned for success in the competitive commercial energy storage market.
Financial Incentives and Investment Landscape
The financial incentives for commercial energy storage projects have never been more robust, primarily due to the foundational support from the IRA and complementary state programs. A deep dive into the first quarter of 2026 reveals critical updates and clarifications that impact project economics and investment decisions.
Investment Tax Credit (ITC) Enhancements
The standalone ITC for energy storage remains a primary driver. Recent Treasury guidance has clarified the ‘beginning of construction’ rules and the ‘placed in service’ deadlines, providing greater certainty for developers. Furthermore, the domestic content bonus credit, offering an additional 10% ITC, has become a significant factor. Developers are now actively seeking US-manufactured components for batteries, inverters, and other balance-of-system equipment to qualify. This has spurred a nascent but growing domestic manufacturing sector for energy storage components, creating a virtuous cycle of policy-driven investment and local job creation.
The ‘energy community’ bonus credit, also an additional 10% ITC, has seen detailed mapping and eligibility criteria released. This allows developers to precisely identify project sites that qualify, often in areas with retired coal plants or significant fossil fuel employment. For commercial projects, this can translate into a substantial increase in project value, making previously marginal sites economically viable. Similarly, the low-income communities bonus credit, up to an additional 20%, is encouraging projects that directly benefit disadvantaged populations, often through community solar-plus-storage models or grid-resilience initiatives for critical infrastructure.
Grant Programs and Loan Guarantees
Beyond tax credits, the DOE’s Office of Clean Energy Demonstrations (OCED) has announced new rounds of funding for long-duration energy storage demonstrations, focusing on technologies ready for commercial-scale deployment. These grants typically cover a significant portion of project costs, de-risking innovative technologies and accelerating their market entry. For commercial developers, partnering with technology providers or research institutions to apply for these grants can be a strategic move to fund cutting-edge projects.
The Loan Programs Office (LPO) has also been active, offering loan guarantees for large-scale, innovative clean energy projects, including energy storage. These guarantees can significantly reduce borrowing costs for developers, making large capital-intensive projects more attractive to private lenders. The emphasis is on projects that demonstrate significant environmental benefits, technological innovation, and strong financial viability. Navigating the LPO application process, which can be rigorous, requires substantial financial and technical expertise.
State-Specific Incentives and Procurement Programs
Many states continue to offer their own incentive programs, often stacking with federal benefits. For instance, some states provide rebates for behind-the-meter storage, performance-based incentives for grid services, or property tax exemptions for energy storage assets. Utilities, under state mandates, are also issuing requests for proposals (RFPs) for energy storage capacity, creating a direct market for developers. These procurement programs often come with long-term contracts, providing revenue certainty and attracting significant investment.
The overall investment landscape for commercial energy storage is incredibly favorable, marked by a confluence of robust federal tax incentives, targeted grant and loan programs, and supportive state policies. However, the complexity of these incentives requires sophisticated financial modeling and a thorough understanding of eligibility criteria. Developers who can master this financial ecosystem will find ample opportunities for growth and profitability.
Regulatory Frameworks and Interconnection Challenges
While financial incentives are crucial, the regulatory framework and interconnection processes often present the most significant hurdles for commercial energy storage projects. The first quarter of 2026 has brought both clarifications and new complexities in these areas.
FERC and RTO/ISO Developments
FERC Order 2222’s implementation continues to be refined across various RTOs and Independent System Operators (ISOs). While the order aims to level the playing field for distributed energy resources (DERs), including storage, challenges persist in operationalizing its principles. Recent RTO filings and FERC approvals have addressed specific market participation models for hybrid resources (e.g., solar-plus-storage), clarification on capacity market rules, and adjustments to bidding parameters. These updates are vital for commercial developers to understand how their assets can participate in wholesale markets and stack multiple revenue streams effectively.
Interconnection queues remain a bottleneck for many projects. While FERC has proposed reforms to streamline the interconnection process, such as moving to a ‘first-ready, first-served’ approach and increasing study deposits, the impact of these changes is just beginning to be felt. Developers are still contending with lengthy study times, high upgrade costs, and uncertainty regarding project timelines. Proactive engagement with RTOs/ISOs and utilities during the early stages of project development is more critical than ever to mitigate these risks.
State-Level Permitting and Siting
At the state level, permitting and siting regulations for energy storage are becoming more standardized but also more stringent in some areas. States are developing specific codes for battery energy storage systems (BESS), addressing fire safety, environmental impact assessments, and land use planning. Local jurisdictions are also playing a larger role, with many municipalities developing their own ordinances for BESS installations. This patchwork of regulations necessitates careful navigation, often requiring specialized legal and engineering expertise.
Some states are exploring ‘fast-track’ permitting processes for renewable energy and storage projects, recognizing the urgency of grid modernization. However, these often come with specific criteria and requirements, such as adherence to certain environmental standards or community benefit agreements. Understanding these local nuances is paramount to avoiding costly delays and ensuring project viability.
Cybersecurity and Grid Resilience
With the increasing integration of energy storage into the grid, cybersecurity concerns have moved to the forefront. Federal agencies, in collaboration with industry stakeholders, have released updated guidelines and best practices for securing critical energy infrastructure, including storage assets. Commercial developers must now incorporate robust cybersecurity measures into their project designs and operational protocols, often requiring compliance with NERC CIP (North American Electric Reliability Corporation Critical Infrastructure Protection) standards for larger, grid-connected systems. This adds another layer of complexity and cost but is essential for maintaining grid stability and protecting national security.
The regulatory landscape for commercial energy storage is maturing, reflecting the technology’s growing importance. While this brings greater certainty, it also introduces more rigorous compliance requirements. Successful developers will be those who can adeptly manage these regulatory complexities, ensuring their projects are not only technically sound but also fully compliant and resilient.
Market Impacts and Future Outlook
The cumulative effect of these US energy storage policy changes in the first three months of 2026 is profoundly shaping the commercial energy storage market. We are observing several key trends and can project an optimistic yet challenging outlook for the remainder of the year and beyond.
Accelerated Deployment and Diversification
The robust incentive structures, particularly the expanded ITC and various bonus credits, are driving an unprecedented acceleration in energy storage deployment across all segments – utility-scale, C&I, and residential. Commercial energy storage projects are particularly benefiting from the ability to stack multiple revenue streams, including wholesale market participation, demand charge management, and grid services. This financial viability is attracting a wider array of investors, from traditional energy players to private equity and infrastructure funds.
Moreover, the focus on long-duration storage through DOE grants and LPO loans is fostering greater technological diversification. While lithium-ion batteries continue to dominate, we are seeing increased investment in alternative chemistries and mechanical storage solutions. This diversification is crucial for addressing different grid needs and enhancing overall grid resilience, moving beyond short-duration applications to provide multi-day storage capabilities.
Supply Chain and Domestic Manufacturing
The domestic content requirements embedded in the ITC are having a tangible impact on the energy storage supply chain. There’s a noticeable shift towards establishing or expanding manufacturing capabilities for battery cells, modules, and other components within the US. This trend, while initially challenging due to existing global supply chains, is expected to reduce reliance on foreign imports, enhance supply chain security, and create domestic jobs. For commercial developers, navigating these domestic content rules will become increasingly important for maximizing incentive capture.
Increased Competition and Innovation
As the market grows and becomes more attractive, competition among developers, technology providers, and integrators is intensifying. This increased competition is, in turn, spurring greater innovation in system design, energy management software, and business models. Companies are exploring new ways to optimize project performance, reduce costs, and offer more compelling value propositions to customers. The emphasis is shifting towards integrated solutions that combine generation, storage, and intelligent controls to deliver maximum economic and grid benefits.
Challenges and Risks Ahead
Despite the positive outlook, several challenges persist. Interconnection queues remain a significant hurdle, potentially delaying projects and increasing costs. Supply chain disruptions, although easing in some areas, can still impact component availability and pricing. Furthermore, the complexity of navigating diverse federal, state, and local policies requires specialized expertise, which can be a barrier for smaller developers. Cybersecurity threats also pose an ongoing risk that requires continuous vigilance and investment.
The regulatory landscape for commercial energy storage is maturing, reflecting the technology’s growing importance. While this brings greater certainty, it also introduces more rigorous compliance requirements. Successful developers will be those who can adeptly manage these regulatory complexities, ensuring their projects are not only technically sound but also fully compliant and resilient.
Conclusion: Adapting to a Dynamic Energy Storage Future
The opening months of 2026 have undeniably set a robust trajectory for commercial energy storage projects across the United States. The intricate web of federal policies, particularly the enhanced Investment Tax Credit and its various bonus provisions, coupled with an increasingly supportive, albeit varied, state-level landscape, is creating an unprecedented environment for growth. This 3-month review highlights a clear governmental commitment to accelerating the deployment of energy storage as a foundational element of a modernized, resilient, and decarbonized grid.
For stakeholders in the commercial energy storage sector, the imperative is clear: continuous engagement with the evolving policy landscape is not merely beneficial but absolutely essential for strategic planning and successful project execution. The financial incentives are significant, but their effective utilization demands a meticulous understanding of eligibility criteria, domestic content requirements, and prevailing wage stipulations. Similarly, navigating the complex regulatory frameworks, from FERC’s wholesale market rules to state-specific permitting processes and increasingly stringent cybersecurity guidelines, requires proactive and informed approaches.
The market is responding with accelerated deployment, technological diversification, and a burgeoning domestic supply chain. This growth, however, is not without its challenges, including persistent interconnection bottlenecks and the inherent complexities of a multi-layered policy environment. Yet, the overall outlook remains overwhelmingly positive, with innovation and competition driving efficiency and creating new opportunities.
As we move further into 2026, the commercial energy storage industry will continue to be shaped by these policy dynamics. Success will hinge on the ability of developers, investors, and technology providers to adapt swiftly, leverage available incentives effectively, and collaborate strategically to overcome regulatory hurdles. The future of US energy infrastructure is increasingly reliant on robust energy storage solutions, and the policies enacted in these early months of 2026 are paving the way for a transformative decade ahead.